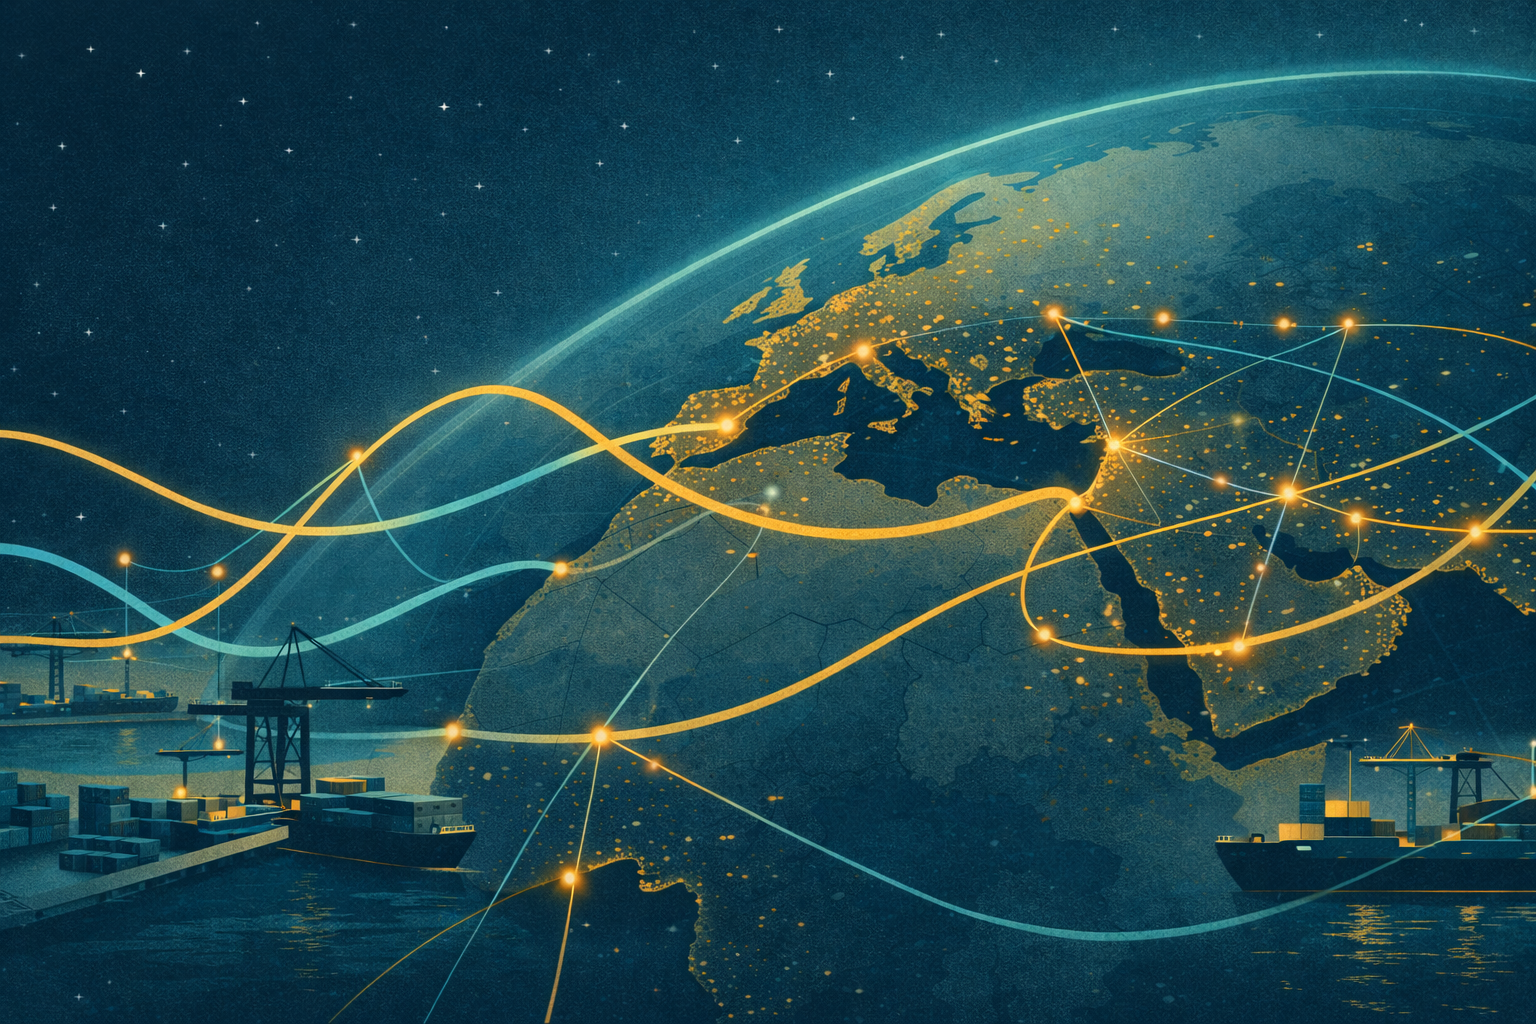
The first lesson from this quarter’s energy updates is that a geopolitical shock does not move cleanly through a company’s accounts. Shell and ExxonMobil have both used first-quarter trading statements to show that higher oil and gas prices can coexist with weaker production, heavier working-capital demands, and earnings that look far more volatile than the underlying business may suggest.
Exxon said stronger oil prices could add about $1.4 billion to upstream earnings compared with the previous quarter. Yet the company also warned that downstream earnings could take a hit of around $5.3 billion because of timing effects linked to derivatives and cargoes that were not delivered during the conflict. The problem is not that the trades were necessarily bad ones. It is that the accounting lands before the physical transaction has fully settled, leaving reported profit exposed to a mismatch between financial hedges and delayed shipments.
Shell’s update carried a different version of the same message. The company lowered its first-quarter integrated gas production guidance to 880,000–920,000 barrels of oil equivalent a day from 920,000–980,000 previously, after disruption in Qatar and constraints in Australia. At the same time, it said oil trading should be stronger, and analysts lifted estimates for first-quarter earnings and cash flow. Shell also warned that net debt would rise, with long-term shipping leases and large swings in working capital weighing on the picture. One quarter, in other words, can now contain buoyant trading, softer output, and heavier balance-sheet strain all at once.
Investors still tend to read a quarter as though prices, volumes, margins, and cash conversion should broadly point in the same direction. During a supply shock, they do not. Shipping routes are interrupted. Cargoes take longer to reach customers. Inventory values jump. Hedges do their job, but create awkward timing differences in the income statement. Companies can be economically stronger than the quarter suggests, or operationally more vulnerable than the headline profit implies. The published numbers are still real, but they are no longer a simple guide to underlying performance.
The burden then shifts to explanation. When the market is already trying to price in a ceasefire, a reopened shipping lane, or another lurch in oil prices, finance teams need to do more than publish a number and move on. They have to show where the distortion sits, how much of it is operational, how much is accounting, and how long it may take to unwind. Exxon has already said the negative timing effects should reverse over time and produce net-positive profit once the underlying transactions are complete. That may reassure investors, but it also underlines how much of the job now lies in translating disorder into something markets can read.
The wider significance reaches well beyond oil majors. Any multinational with long shipping routes, commodity exposure, hedging programmes, or heavy working-capital cycles can find that a conflict turns the quarter into a poor summary of the business. Price spikes may dominate the headlines, but the harder story often sits inside the accounts: delayed cargoes, strained cash flow, and profits that tell only part of what happened.