
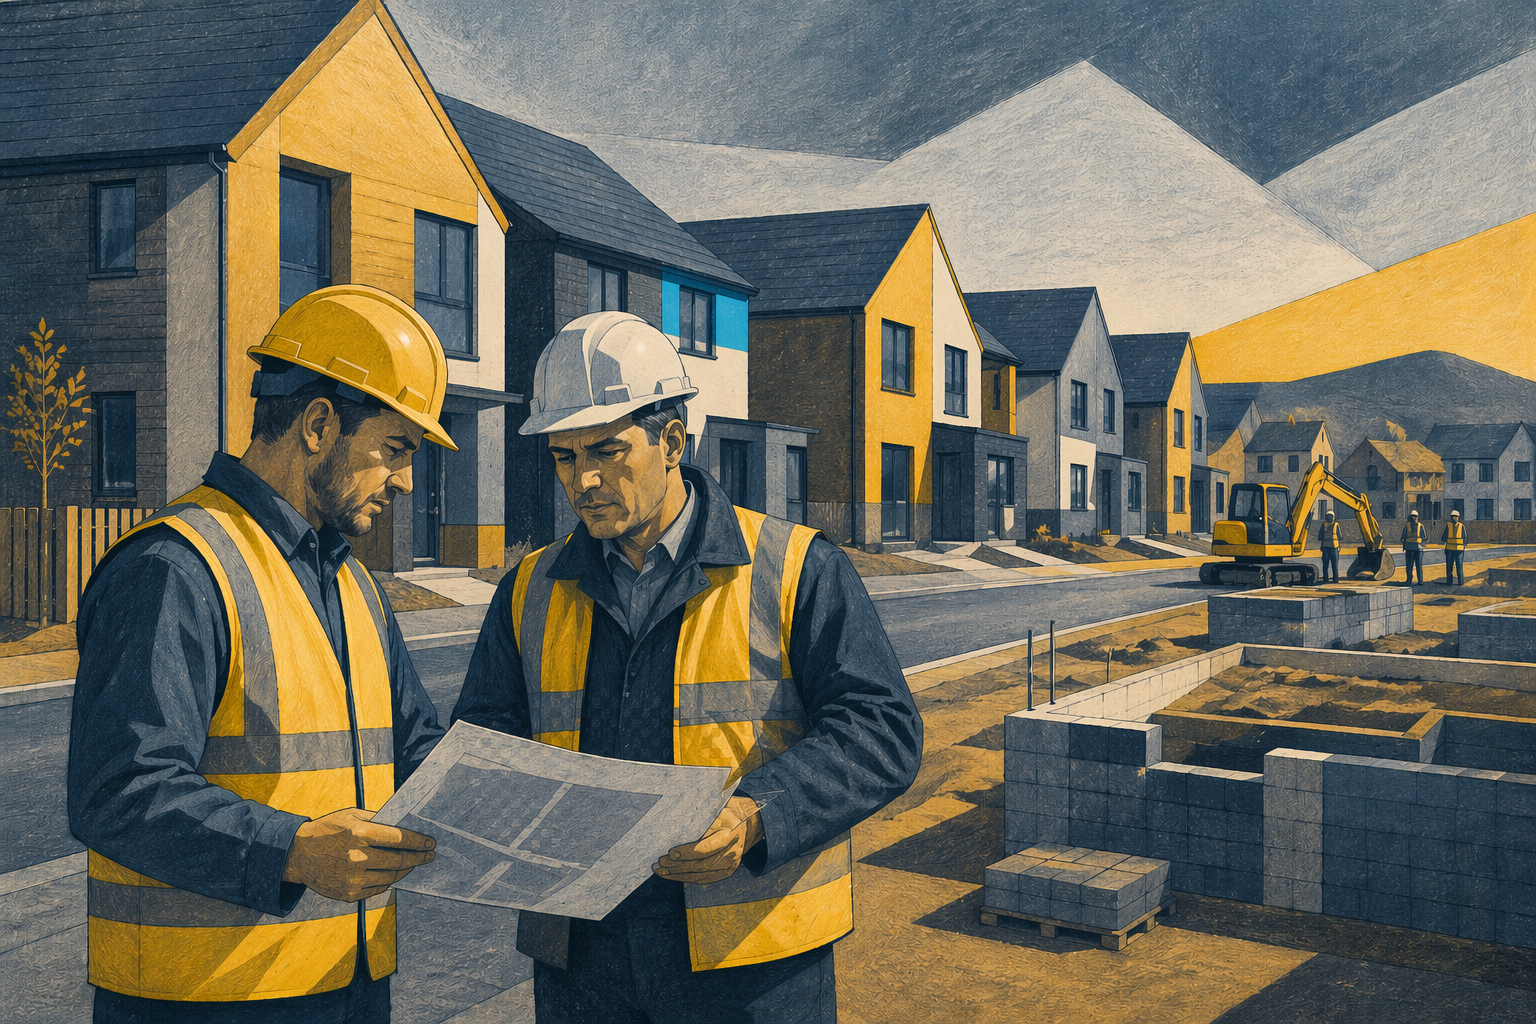
Bellway expects to complete fewer homes during its 2027 financial year despite reporting higher revenue and profits for 2026, as mortgage affordability pressures and rising construction costs continue to affect the British housing market.
The housebuilder is targeting between 9,000 and 9,400 completions in the year to July 2027, compared with 9,695 during the preceding financial year. Its annual results, published on 13 October, show revenue increasing 13.6% to £3.16bn, while underlying pre-tax profit rose 5.7% to £305.7m.
Housing completions increased 10.8% from 8,749 in 2025, supported by the company’s stronger opening order book. The average selling price reached approximately £324,400, up from £316,400 a year earlier, although the underlying operating margin declined from 10.9% to 10.1%.
The margin reduction indicates that higher revenue has not translated into an equivalent improvement in operating profitability. Construction cost inflation, sales incentives and the composition of completed properties continue to affect the financial return Bellway earns from its developments.
The company’s forward order book at 2 October comprised 4,981 homes worth £1.44bn, compared with 5,285 homes valued at £1.53bn a year earlier. The lower level of committed sales leaves Bellway entering the current financial year with less forward visibility than it enjoyed in 2025.
Recent reservation activity also points to subdued private buyer demand. During the nine weeks from 1 August, the private reservation rate excluding bulk sales was 0.45 homes per outlet per week, compared with 0.48 during the corresponding period last year.
Mortgage affordability remains a significant constraint. Although the relationship between mortgage rates and buyer demand varies according to individual circumstances, higher borrowing costs reduce the amount some households can afford to spend and may encourage prospective purchasers to delay decisions.
Bellway expects a greater contribution from bulk sales during FY2027 to support completions and cash generation. Such transactions, which can involve agreements with institutional purchasers, provide an alternative route for developers to sell completed homes but may generate lower margins than conventional individual sales.
The company completed 615 homes through bulk sales during FY2026, compared with 308 a year earlier. A further increase in that proportion would change the composition of its revenue even if overall selling prices remained comparatively stable.
Underlying operating margins are expected to decline again during the current financial year. Bellway said cost efficiencies and improvements to its land portfolio would help offset pressure, but acknowledged that these measures would not fully compensate for lower output, construction inflation and higher sales incentives.
The financial results nevertheless demonstrate a stronger cash position. Adjusted operating cashflow rose 36% to £868.6m, while year-end net cash increased to £157.7m from £41.8m. The improvement has supported a £150m share buyback programme for FY2027, following a programme of the same size announced in October 2025.
Bellway is also pursuing selective investment in land while managing expenditure on lower-margin sites. The approach reflects the need to maintain development opportunities for future years without committing excessive capital while demand remains uncertain.
The government’s proposed Your First Home scheme could alter the market outlook. Bellway has suggested that the support available to eligible first-time buyers may eventually increase its annual completions by approximately 10%, although that assessment depends on the scheme’s final design and the availability of mortgage finance.
There is also a potential short-term effect while details remain unresolved. Prospective purchasers may defer buying if they expect to qualify for support once the programme becomes available, leaving housebuilders to manage demand during the period before implementation.
Bellway’s results reflect the broader pressures affecting volume housebuilders, which must balance construction expenditure, working capital and sales incentives against household purchasing power. The company’s financial position provides capacity to withstand weaker trading, but the latest completion guidance shows that management expects those pressures to persist during FY2027.
Its medium-term ambition remains to expand output and profitability as market conditions improve. Achieving that growth will depend on stronger reservation activity, the cost of financing new homes and the ability to improve margins across its development portfolio.
You must be logged in to post a comment.