
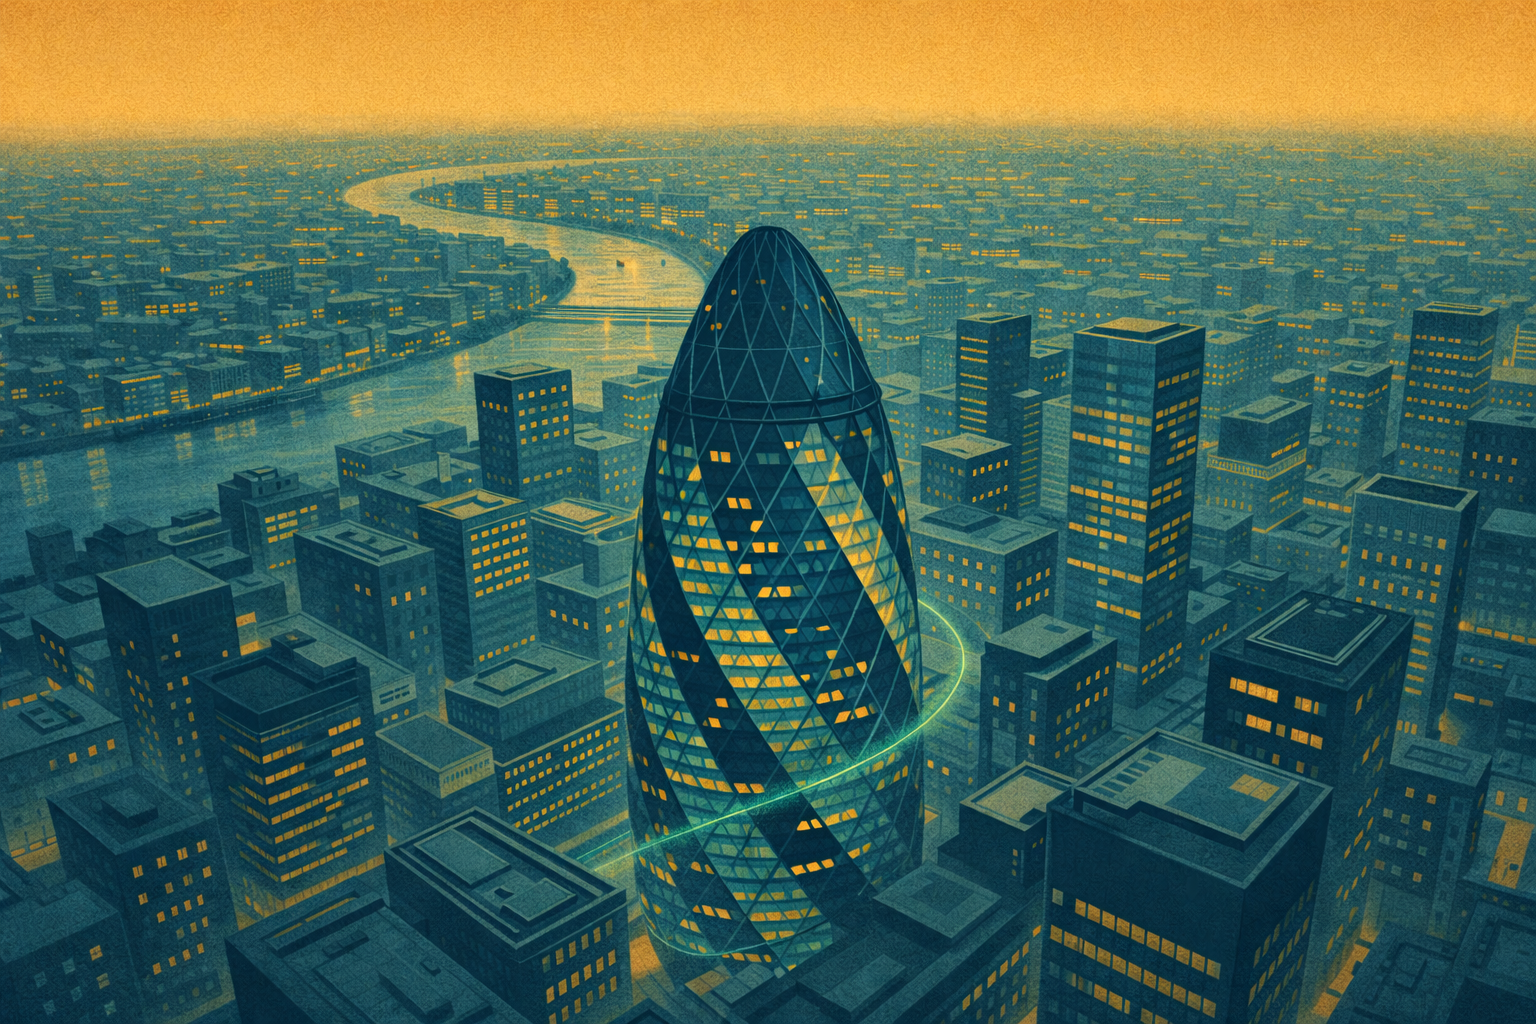
Artificial intelligence companies took more than 700,000 sq ft of London office space during the first half of 2026, more than double their total for the whole of last year as fast-growing technology businesses expand their physical presence in the capital.
The figures come from research produced by Opportunity London with JLL. AI businesses accounted for as much as a third of central London office take-up during the second quarter, adding a new source of demand to a property market still adjusting to hybrid working.
Central London recorded 2.6m sq ft of office lettings in the second quarter. A further 4.9m sq ft was under offer, while occupiers were actively looking for another 14.3m sq ft, according to the research.
Several US technology businesses are contributing to the shift. Anthropic has agreed to take around 158,500 sq ft at One Triton Square, while OpenAI has committed to approximately 95,500 sq ft near King’s Cross. Replit has also selected London for its first international office.
The activity provides a counterpoint to predictions that AI will simply reduce office demand by replacing white-collar roles. During the current investment cycle, companies developing AI systems are hiring specialised engineering, research and commercial teams and competing for high-quality buildings close to established technology and research clusters.
Location is particularly important. King’s Cross, Euston and Fitzrovia combine transport links with universities, research institutions, investors and existing technology employers. For businesses competing globally for specialist employees, those networks can influence property decisions even where staff work flexibly.
The demand is also highly selective. Technology companies tend to seek modern buildings with strong connectivity, sufficient electrical capacity and flexible layouts. Sustainability credentials and access to transport can be important to employers trying to attract workers who do not expect to attend an office five days a week.
That contributes to a widening divide in commercial property. Prime offices can attract strong demand even when the wider market carries substantial vacancy, while older stock may require expensive refurbishment to meet energy standards and occupier expectations.
AI companies are also competing with banks, law companies and other professional-services employers for many of the same buildings. A limited supply of modern space in preferred locations can consequently support rents even when total office occupancy remains below pre-pandemic patterns.
The wider investment market has also improved. Around £7.4bn was invested in London commercial property during the first half of 2026, up 14% year on year, with central London offices accounting for £3.7bn.
The physical expansion of AI has implications beyond office landlords. Growing technology clusters increase demand for housing, transport, electricity, data centres and network connectivity. The sector’s infrastructure footprint therefore extends well beyond the computing facilities most obviously associated with AI.
Growth rates need to be treated cautiously because many AI businesses are expanding from small starting points. Technology leasing can also be volatile if venture investment weakens or companies take space ahead of revenue and later reduce headcount.
The current figures nevertheless show capital and employment becoming visible in property decisions. AI investment in London is no longer confined to funding announcements and computing infrastructure: it is influencing which office districts attract tenants and which buildings command investment.
For landlords and developers, the opportunity comes with a specific requirement. The sector is not creating equal demand for every office. Buildings that can satisfy power, connectivity, sustainability and location expectations are benefiting first, reinforcing the shift towards a smaller pool of high-specification workspace within a much larger London market.
You must be logged in to post a comment.